Recent Search
Popular Searches


The UK Parliament on Monday passed legislation allowing Prime Minister Theresa May to invoke Article 50 of the Lisbon Treaty. She is preparing to trigger Brexit in the last week of March and faces the simultaneous challenge of pulling Britain out of the EU on good terms while navigating Scotland’s renewed bid for independence. Scotland voted to remain in the EU. Scottish First Minister Nicola Sturgeon plans to now start the process of getting permission to hold a second independence referendum at some point between the fall of 2018 and the spring of 2019, by which time she expects the terms of the Brexit deal to be clear.
Kuwait stated its intention to support the extension of the OPEC oil production cut agreement that ends in June citing that it will accelerate the rebalancing of the global oil market. Iraq and Angola have also signalled willingness to extend while the most influential member of OPEC, Saudi Arabia is not yet committal about the direction it will take.
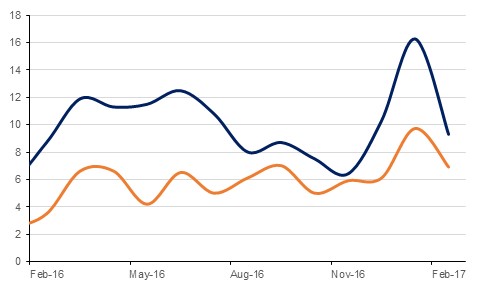
The NAB Business confidence in Australia fell 3 points m/m to 7 and business conditions declined 7 points to 9 after rising 4 points and 6 points to 10 and 16 respectively in the previous month. Sentiment in Australia has recently been volatile in view of Chinese policy makers revising the GDP growth target to 6.5% from previous 6.5% to 7.0% range.
In India, CPI Inflation is due today and is likely to have increased to 3.4% year on year from 3.2% in January though is likely to fall again to below 3% by May, pressured by a likely bountiful spring harvest and more-favorable base effects. Annualised inflation is likely to remain below the RBI's 4% medium-term target through to March 2018.
 Source: Bloomberg, Emirates NBD Research
|
| Time | Cons |
| Time | Cons |
| Germany CPI y/y | 11:00 | 0.6% | ZEW Surveys | 14:00 | N/A |
| US NFIB Small Business Optimism | 14:00 | 105.6 | US PPI Final Demand m/m | 16:30 | 0.1% |
Source: Bloomberg.
Most fixed income participants sat on the sidelines yesterday, waiting to interpret the outcome of the FOMC meeting tomorrow. Yields on UST rose in anticipation of the widely assumed 25bp Fed rate hike with 2yr and 10yr closing at 1.37% (+2bps) and 2.63% (+5bps) respectively. Performance of the sovereign bonds in the Europe was mixed with Bund yields declining a bp to 0.47% and Gilt yields getting pushed up another 2bps to 1.24% by the increasing uncertainty around the final terms negotiated on Brexit.
GCC bonds reflected surprising resilience amid soft oil prices and large new issue pipeline. Credit spreads on liquid UAE bonds were down 3bps to 127bps thereby dragging average yield on the BUAEUL index to 3.16% (-2bps).
In the primary market, Kuwait raised $ 8 billion yesterday and Saudi Arabia has mandated banks for a possible international sukuk sometime soon. As was expected, final pricing on AA/stable rated Kuwait tightened materially from the initial guidance with $3.5 billion 5yr deal closing at T+75bps and $4.5 billion 10yr at MS+ 102.7bps.
This morning, AUD has softened against the other majors after NAB surveys showed reductions in business conditions and confidence in February (see above). Currently, the AUDUSD pair trades at 0.7560, having moved back below its 50 day moving average of 0.7575 and the one year 61.8% Fibonacci retracement of 0.7571. While the pair remains below these levels, there is a vulnerability to further losses and we see the path of least resistance being a descent towards 0.7409, the one year 38.2% Fibonacci retracement.
Developed market equities closed marginally higher even as investors remain cautious ahead of the Fed meeting starting later today. While the S&P 500 index closed flat, the Euro Stoxx 600 index gained +0.4% helped by strength in commodity stocks.
Asian equities are trading higher this morning led by strength in Indian equities. India’s Nifty index was trading +1.7% at the time of this writing as investors are enthused by state election results over the weekend.
Regional equities continue to drift lower with the Bloomberg GCC 200 index losing -0.7%.
The DFM index was a notable exception with gain of +0.6% even as trading was dominated by small cap stocks. Gulf Finance House (+7.0%) accounted for nearly 43% of total volume on the DFM. Elsewhere, the Tadawul dropped -0.7% on the back of weakness in banking sector stocks with Samba losing -3.4% and NCB declining -1.3%.
Oil markets took a breather yesterday, closing effectively unchanged ahead of today's OPEC monthly oil report. Production numbers are likely to show another month of strong compliance with OPEC's agreement to limit output but the impact of the decline is waning against the consistently strong numbers coming out of the US. The long-dated backwardation in Brent spreads continued to narrow yesterday, moving to around USD 0.30/b for both the Dec 17-18 and 17-19 spreads, showing how flat the curve has become. The WTI curve closed back in contango, albeit at tentative levels.


 Emirates NBD Research