Recent Search
Popular Searches


Oil benchmarks weakened a second week running as concerns over supply constraints gave way to emerging anxiety about crude demand in 2019. Brent prices fell 0.8% over the course of the week to close at USD 79.78/b while WTI lost more than 3% to close back below USD 70/b. Strong Chinese refinery demand in September (12.49m b/d) was an outlier in otherwise weak economic growth in Q3: GDP rose 6.5% y/y compared with 6.7% in the previous three months. The full impact of the US-China trade war will hit markets in 2019 and could act as a considerable drag on oil demand next year, raising the possibility of the market returning to surplus.
The WTI market already appears to be pricing in that outcome as the forward curve closed in contango for the first five months. The flip of the curve is a significant turnaround from the backwardation over as much as USD 2.5/b on the 1-2 month spread that WTI saw this summer. The move into contango reflects the persistent upward climb in US production, despite a shortage of takeaway pipeline capacity, and a steady increase in US crude stocks. So far the move in the US benchmark hasn’t brought down the Brent curve in sympathy and the uncertainty over whether other OPEC members can replace the drop in Iranian volumes will likely keep Brent better supported until demand weakness becomes more apparent. Indeed, Brent-WTI closed again back below USD 10/b at the end of the week and we expect the spread will remain wide until Q3 2019.
The US added four rigs last week, up 137 rigs y/y, and bringing the total up to 873. If the forward curve continues to weaken and deepen into contango the rig count will eventually begin to flatten out. A much more immediate response, however, has shown up in speculator positions. Net length in WTI fell by 37k contracts last week as long positions were cut for a sixth week in a row and shorts began to grow more confident. Brent net length also plummeted by more than 66k contracts thanks to nearly 65k long positions coming out of the market. We suspect the decline in Brent net-length reflects recent profit taking more than a revaluation of the market outlook. Our forecast for Brent is to move back into a USD 70-80/b range once the market has a firmer understanding of the scale of decline in Iran’s production.
The divergence between international and US markets is manifesting itself more evidently in inventory levels. Product stocks continue to remain tight in Singapore—particularly in fuel oil and light distillates—while in the US overall inventories are on a steady upward trend. Crude stocks in the US have risen four weeks in a row and are down only 8m bbl so far this year compared with a draw of 55m bbl for 2017 as a whole. With storage emptied steadily last year inventory tanks beckon as a destination of last resort for US crude producers and expect they will steadily build until pipeline constraints ease in H2 2018.
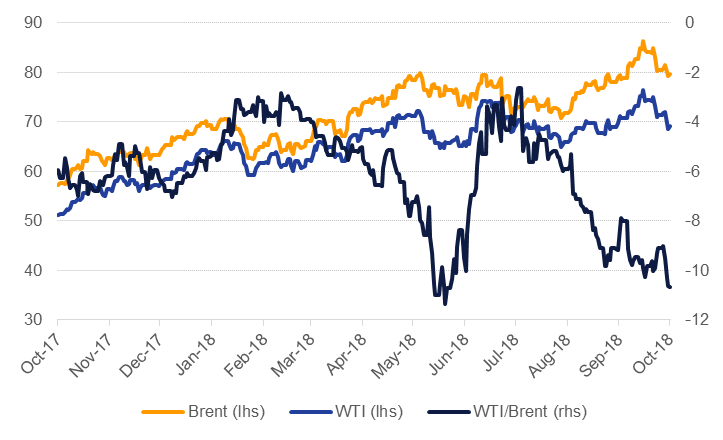 Source: EIKON, Emirates NBD Research.