Recent Search
Popular Searches


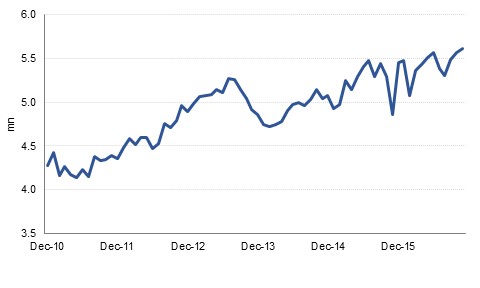
Both Eurozone consumer confidence and US existing home sales came in stronger than expected yesterday, but equity markets closed lower on the day. Existing home sales rose to the highest level since February 2007 in November, with contract closings at 5.61mn. There is a raft of US data due today including the third estimate of Q3 GDP, personal consumption and core PCE, November durable goods orders and personal income and spending for November.
The main event in the GCC today is expected to be the release of the 2017 Saudi budget. Bloomberg reports that the budget may show a path to a surplus by 2020. This would require further expenditure reform as well as measures to boost non-oil revenues, although a surplus by 2020 will likely depend on higher oil prices in the next couple of years as well. Yesterday officials indicated that a further cut to fuel subsidies is being considered, along with cash transfers to help offset the impact of higher fuel prices on low-income households.
Dubai’s ruler approved the 2017 budget with a AED 2.5bn (0.6% of GDP) budget deficit according to the official statement. This follows two years of balanced budgets. Infrastructure spending is set to increase by 27% next year as Dubai ramps up preparations for the Expo2020. We expect infrastructure spending to underpin Dubai’s economic growth over the next three years. More than 3500 new jobs are expected to be created next year with wages & salaries accounting for 33% of total expenditure. On the revenue side, the budget projects higher fee revenue in 2017, accounting for 76% of total revenue. Tax and customs duties is expected to contribute 16% of the total, with the remainder coming from oil revenue and investment income.
 Source: Bloomberg, Emirates NBD Research
|
| Time | Cons |
| Time | Cons |
| US Chicago Fed Activity | 17:30 | -0.1 | US Q3 GDP (third estimate) | 17:30 | 3.3% |
| US Durable Goods Orders | 17:30 | -4.8% | US Personal Income | 19:00 | 0.3% |
| US Personal Spending | 19:00 | 0.3% | US Leading Index | 19:00 | 0.1% |
Lacking any material economic news and heading into the year-end holidays, fixed income markets had a day of range bound trading yesterday. Sovereign bonds across the developed world edged slightly higher up with yields on 2yr and 10yr treasuries closing at 1.19% (-3bps) and 2.53% (-3bps) respectively while those on 10yr Bunds and Gilts closed at 0.24% (-2bps) and 1.39% (-1bp) respectively.
Following the benchmark lead, cash corporate bonds were all in green and CDS levels on US IG and Euro Main narrowed marginally to 67bps (unchanged) and 69bps (-1bp) respectively.
Stable oil prices and lack of new issues supported GCC bond prices at mostly unchanged levels albeit with a slight upward bias in line with lower benchmark yields. BUAEUL index closed with YTW at 3.20% (-3bps) amid thin trading volumes. Pipeline for primary market in the first quarter next year looks healthy. Kuwait’s Warba Bank yesterday mandated nine banks for a possible $250 million sukuk deal.
Developed market equities gave up a part of their recent gains with liquidity remaining low heading into the year-end. The S&P 500 index and the Euro Stoxx 50 index dropped -0.3% each. Asian equities are trading lower this morning on the back of weakness in Japanese equities. The Nikkei index was trading -0.4% at the time of this writing.
It was a mixed day of trading for regional equities. The Tadawul gained +0.4% ahead on the anticipated budget announcement later today. In terms of stocks, Arabian Pipes and Saudi Steel Pipes rallied +3.7% and +5.5% respectively after receiving orders from Saudi Aramco. Arab National Bank dropped -0.9% after proposing a lower dividend than last year.
Following the American Petroleum Institute’s (API) report late on Tuesday that US crude stockpiles declined by 4.15mn barrels last week, the Energy Information Administration (EIA) data released yesterday instead showed a rise of 2.3mn bpd last week. This surprised the market, which had been expected a decline of 2.5mn barrels and oil prices declined on the news. Prices have recovered somewhat this morning with Brent back above USD 54/b. API represents industry while the EIA is a government agency.
USD gave back some of its recent gains overnight as oil prices declined and stock markets closed lower. US economic data is likely to set the tone today, with very little economic data elsewhere.


 Emirates NBD Research