Recent Search
Popular Searches


The Strait of Hormuz has effectively been shut in commercial terms as vessels avoid the critical chokepoint for global energy. Following the start of the US – Israel air war against Iran, members of Iran’s Islamic Revolutionary Guard Corp (IRGC) have warned ships not to pass through the strait with the most explicit warning coming from a commander overnight on 2 March 2026, saying that forces would “set fire to any ship” attempting to pass through the strait.
 Source: Bloomberg, Emirates NBD Research.
Iran has repeatedly threatened during previous periods of crisis and conflict that it would shut the Strait of Hormuz but it has never taken action to fully stop the flow of vessels. Several oil and product tankers have been attacked since the conflict began on 28 February 2026.
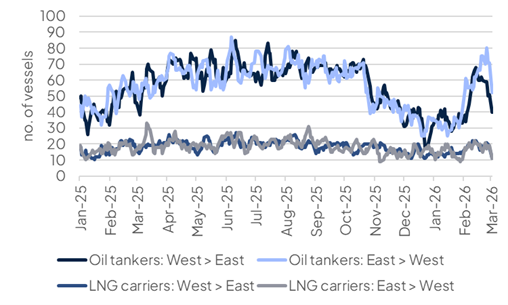
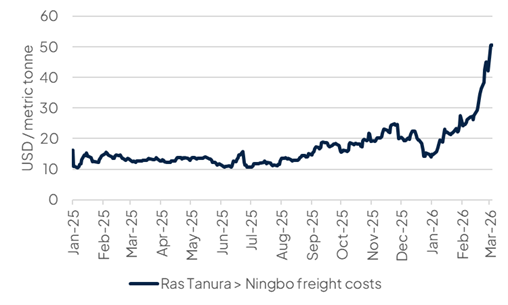
Both crude oil tanker and LNG carrier volumes passing through the Strait of Hormuz have dropped sharply in recent days following a recent spike when shipping firms were likely front-loading cargoes ahead of any imminent conflict. Maritime insurance premiums have also spiked and freight costs have jumped. Middle East to China dirty tanker freight costs have jumped to more than USD 50/metric tonne according to Bloomberg pricing.
 Source: Bloomberg, Emirates NBD Research.
Shipping disruptions lead to production shut-ins
The disruption to the Strait of Hormuz is compounding the effect of attacks on critical energy infrastructure in the Gulf. The Ras Tanura refinery in Saudi Arabia has ceased operation after coming under attack while the Ras Laffan LNG terminal in Qatar has suspended production of LNG while the strait is blocked.
Roughly 20% of global seaborne traded oil and products passes through the Strait of Hormuz (circa 20m b/d) with a similar scale of global flows of LNG. The UAE and Saudi Arabia do have pipeline alternatives that allow them to bypass the strait to continue to export crude oil: the Abu Dhabi Crude Oil Pipeline to Fujairah with an estimated capacity of close to 1.8m b/d and the East-West Pipeline to Yanbu on the Red Sea with an estimated capacity of around 5m b/d. There is no similar alternative for LNG to shift to piped gas, however.
Prices respond to new fundamentals
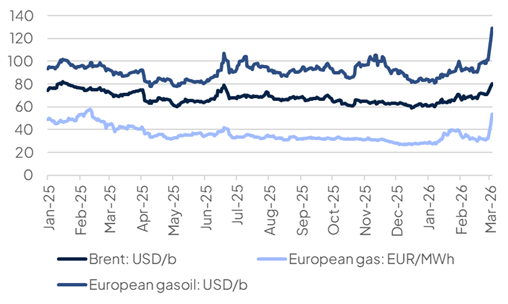
Crude oil, products and natural gas prices have risen in response to the substantial disruption to shipping from the Gulf. Brent futures had pushed to more than USD 80/b as of 3 March 2026, up more than 11% since the start of the conflict, while European gasoil has risen nearly 28% at USD 962/tonne and European natural gas futures had risen by almost 67% to EUR 53.37/MWh as of 3 March 2026.
 Source: Bloomberg, Emirates NBD Research.
Our long-standing interpretation of geopolitical risks is that if they lead to a change in fundamentals, then that supports a change in views and forecasts. The effective shutting of the Strait of Hormuz is a change in the fundamental picture for energy exports from the GCC and will support prices at an elevated level.
What is unknowable is the duration of the disruption to oil, product and gas exports. US President Donald Trump has provided equivocal estimates of how long operations against Iran will take, saying potentially as long as “four to five weeks.” Assuming that the conflict at least persists until the end of March and oil prices sustain at around current levels, we are revising our Q1 2026 average for Brent to USD 70/b, up from USD 63/b previously. For WTI, we now expect a Q1 2026 average of USD 66/b, up from 58/b previously.
As the scope and impact of the conflict becomes more apparent we will revise our expectation for oil prices in the rest of the year accordingly.